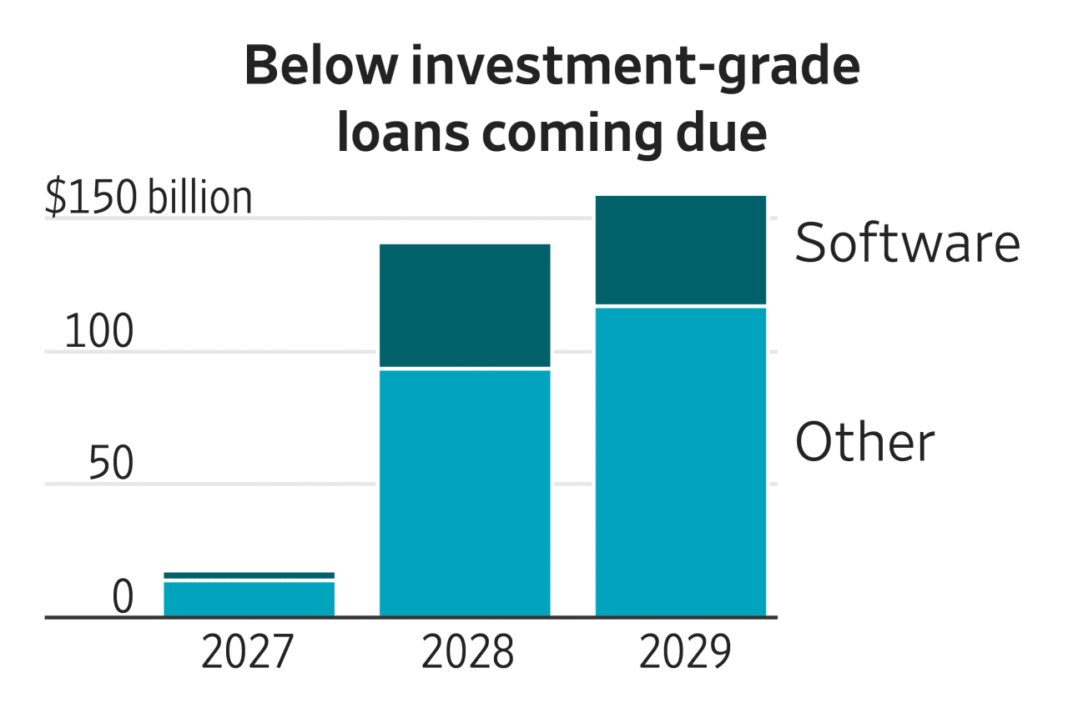
A growing wave of corporate debt tied to private-equity-backed companies is drawing attention from investors and analysts. Roughly $300 billion in risky loans will come due in 2028 and 2029. Software firms account for about one-third of that total, according to data on the looming maturities.
The concentration in software is notable because the sector has faced pressure from higher interest rates and tighter financing conditions. Many of these loans were issued when rates were lower and credit was easier to obtain. Companies now face refinancing at potentially higher costs.
Private-equity firms typically use debt to fund acquisitions, loading portfolio companies with obligations that must be repaid or refinanced. When those debts mature during periods of tight credit, borrowers can struggle to secure new terms. The result is a so-called debt wall—a cluster of maturities arriving within a short window.
Software companies carry specific risks. Their cash flows can be volatile, and many rely on recurring revenue that may slow during economic downturns. Lenders and investors are watching whether these firms can generate enough cash to service existing debt or attract new financing.
The scale of the maturities has prompted comparisons to past credit cycles. Some analysts note that while the total is large, it remains a fraction of the broader corporate debt market. Others warn that the overlap in timing could strain lenders and private-equity sponsors alike.
Market participants are monitoring refinancing activity closely. Early signs suggest some borrowers are seeking extensions or negotiating amended terms with creditors. Others may turn to private credit funds, which have expanded rapidly and can offer alternative financing options.
How the debt wall resolves will depend on interest-rate trends, economic conditions, and lender appetite for risk. For now, the 2028 and 2029 maturities serve as a reminder of the leverage embedded in private-equity-backed businesses. Software firms sit at the center of that exposure.